
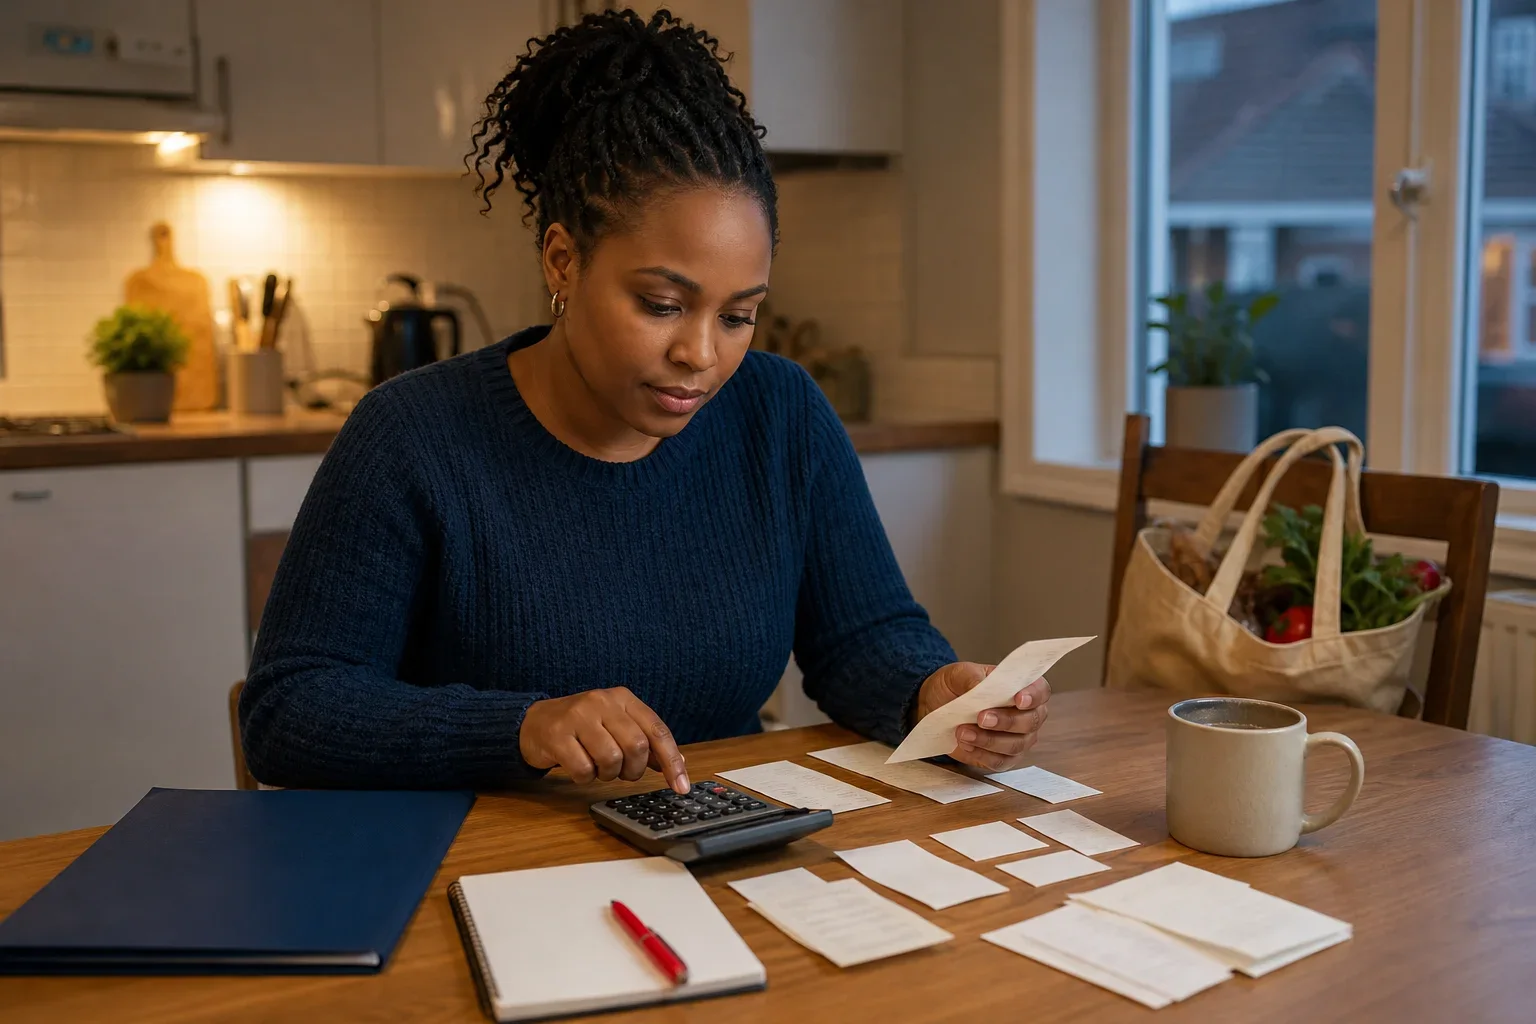
Quick loan instalment amount is a useful figure to check before accepting a loan, but it cannot be viewed on its own. A payment may seem manageable when you focus only on the money coming in this month. It can become difficult when debit orders, food, transport, school needs and an unexpected expense all arrive at once. The practical question is whether you can make the repayment in full, on its due date, while still covering the costs that keep your household running.
A simple affordability check does not need complicated financial language. Start with the income you can reasonably expect before the repayment date, subtract the expenses you cannot avoid, allow for costs that do not happen every month, and leave some room for the unexpected. Then compare what remains with the proposed payment and the total amount you will repay. If the numbers are too tight before you sign, it is better to pause and ask questions than to rely on a hopeful estimate. Reviewing the quick loan instalment amount this way helps you see pressure before it becomes a missed payment.
How to test a quick loan instalment amount
A quick loan instalment amount should be tested against your actual budget, not against the maximum payment you think you might manage in a good month. Use take-home income rather than your full salary before deductions, and include only income that is regular and reasonably certain. If your income varies, base the calculation on a lower typical month rather than the best one.
Write down the repayment date and look at the money that will be available before that date. A weekly or fortnightly payment can still affect a monthly budget, so convert your view into the same period as the loan repayment. For example, do not compare one month’s rent with only one week’s income. The timing matters as much as the total, especially when several debit orders come off near payday.
Start with money coming in
List salary or wages after deductions, regular maintenance where applicable, and any other dependable income. Leave out overtime, commissions, casual work or help from family unless you are confident it will be available on time. Depending on uncertain income to cover a fixed repayment can make an ordinary month feel much tighter.
Next, check whether any part of that income is already committed before you receive it. Existing debit orders, deductions, repayments or agreed household contributions reduce what you can use. The amount left after those commitments is more useful than the figure shown on a payslip.
Subtract essentials before flexible spending
Essentials are the costs you need to maintain everyday life and meet existing responsibilities. Put rent or bond payments, electricity, water, food, transport to work or school, medical needs, insurance, child-related costs and existing debt repayments near the top of your list. If you share a household, use the amount you are genuinely responsible for paying, rather than assuming another person will always cover a shortfall.
Be honest about food and transport. These categories are sometimes underestimated because they are bought in smaller amounts throughout the month. Review recent bank statements, till slips or transport spending where possible, then use a normal month as your guide.
Calculate what is genuinely left
After subtracting essential expenses, note the amount that remains before non-essential spending. This is not automatically spare money. It must still cover changing costs, the proposed loan payment and a buffer. If the remaining figure is lower than the repayment, the payment does not fit based on the information in front of you.
If the figure is only slightly higher, treat that result carefully. A budget that works only if nothing changes is fragile. Compare that margin with the quick loan instalment amount and consider whether it leaves enough room for the rest of the month. A manageable repayment should leave enough room that one ordinary disruption does not force you to miss another important payment.
Quick loan instalment amount and your full costs
This section focuses on quick loan instalment amount. The repayment figure needs to sit alongside every cost connected to the agreement, including what you will repay in total and when each payment is due. The cash received can solve an immediate need, but it is not the true cost of the commitment. Ask for the repayment schedule and read it slowly before you agree.
Check how many payments there are, the amount of each one, the repayment dates and the total amount payable. A lower individual payment may be spread over a longer period, while a larger payment may put more pressure on the next payday. Neither option is automatically suitable. The useful comparison is the one that shows whether your normal income can cover the scheduled payments without disrupting essentials. Put the quick loan instalment amount beside the full repayment total so neither figure is considered in isolation.
When considering quick loans, write the total repayment next to the cash you expect to receive. The difference helps you understand the full commitment rather than judging it only by the amount paid into your account. It also makes it easier to compare different proposed terms on the same basis.
Include costs that are not due every month
Irregular expenses are one of the most common reasons a budget looks comfortable on paper but feels difficult in real life. School items, uniforms, medical visits, vehicle repairs, annual renewals, family events and seasonal electricity use may not be monthly, yet they still need funding. Transport can also change when a vehicle needs attention, a route changes or work shifts vary.
Look ahead to the full repayment period, not just the next few weeks. If a school payment or vehicle licence is likely to fall during that period, set aside a realistic portion of your money for it now. A quick loan instalment amount that fits this month may not fit next month if you leave those known costs out.
Keep a buffer for ordinary surprises
A buffer is money left unassigned after the essentials, changing costs and repayment have been considered. It is not a luxury line in the budget. It gives you some room when groceries cost more than expected, a child needs something for school, data runs out or transport costs rise.
There is no single buffer amount that suits every household. What matters is that the remaining amount is meaningful for your circumstances and does not depend on skipping food, delaying an existing bill or borrowing again. If no buffer remains after the quick loan instalment amount is included, the proposed payment may be too close to your limit.
When a quick loan instalment amount does not fit
A quick loan instalment amount does not fit simply because you need the cash today; it fits only when the repayment can be made alongside your normal responsibilities. Do not solve a short-term gap by creating a predictable shortfall in the following month. Recheck the calculation using lower income, higher transport or grocery costs, and one small unexpected expense.
If the result is negative, or leaves virtually nothing after essentials, do not ignore the warning. Ask whether a different amount, different repayment timing or another approach would be more realistic. It may also help to discuss the situation with the person or organisation you need to pay, as they may explain available payment arrangements.
Loan4Debt describes applications as being assessed for affordability and eligibility. That makes your own preparation useful: have a clear picture of income, existing repayments and regular expenses before you discuss terms with a consultant. Clear information helps you ask better questions and understand whether the proposed repayment suits your situation.
Questions to ask before you accept
- What is the total amount I will repay, not only the amount I receive?
- On which dates will every payment be due?
- What happens to my budget after rent, food, transport and current debit orders?
- Which irregular costs are likely during the repayment period?
- How much money will remain if an ordinary unexpected expense occurs?
Write the answers down rather than relying on memory during a stressful time. If a term is unclear, ask for it to be explained in everyday language. A responsible decision is easier when you understand both the immediate benefit and the future commitment. This also gives you a clear basis for deciding whether the quick loan instalment amount is genuinely sustainable.
If you are comparing instant cash loans immediate payout, keep the same budget method for each option. Faster access to funds does not remove the need to check the repayment date and total cost. Compare like with like so that one proposal is not judged only by speed and another only by its payment amount.
Frequently asked questions
1. Which expenses should I subtract first?
Subtract the costs that protect your home, food, ability to travel, health and existing commitments first. These usually include accommodation, utilities, groceries, transport, insurance, child-related needs and current repayments. Only after these are covered should you assess whether money is available for another fixed payment.
2. Why is the total repayment more important than the cash received?
The cash received shows the immediate amount available for the need you are facing. The total repayment shows the full amount that must come from future income. Looking at both prevents you from treating the amount paid out as if it were the complete cost of the arrangement.
3. How should I handle irregular school or transport costs?
List known irregular costs and estimate when they are likely to occur during the repayment period. Divide annual or occasional costs into smaller monthly amounts where that helps you plan. If you cannot set anything aside for them after the proposed payment, your budget may need another look.
4. Can a quick loan instalment amount be affordable if my income changes?
It may be harder to judge when income varies, because the repayment remains fixed even when earnings do not. Base your budget on a cautious income figure that reflects a quieter or lower-earning period. If the repayment works only in your strongest month, it carries more risk than it first appears.
5. What should I do if the repayment leaves no buffer?
Pause before accepting and review the budget for items that were missed or underestimated. Consider whether the amount, timing or overall commitment needs to change, rather than assuming you will make it work later. For general information about legal institutions, the Department of Justice provides public resources, but individual financial decisions should be considered carefully in relation to your own circumstances.
6. Should I use my bank balance as my affordability check?
Your current balance is only a snapshot and may include money needed for expenses due later in the month. A budget looks forward to the repayment date and accounts for bills that have not yet left your account. You can also review official information from your own financial provider, such as Capitec Bank, alongside your statements and repayment schedule.
7. What information should I have ready to discuss terms?
Have your expected take-home income, current repayments, essential monthly costs and known irregular expenses ready. Note the dates on which income and important bills are due. This preparation makes it easier to ask focused questions about whether a proposed payment is workable.
Before you accept a repayment
Use this short check to test whether the proposed payment works with your regular income and household commitments.
✓ Use reliable take-home income
Base the calculation on income you can reasonably expect before the repayment date.
✓ Pay essentials on paper first
Subtract accommodation, food, transport, utilities, existing repayments and other necessary costs.
✓ Add irregular expenses
Include known school, vehicle, medical and seasonal costs that may arise during the repayment period.
✓ Check the full commitment
Review every due date and the total amount payable, not only the cash received.
✓ Leave breathing room
Make sure some money remains for ordinary unexpected costs after the repayment is included.
Choose a repayment you can carry
A clear budget turns a proposed repayment into a practical decision instead of a guess. Check essentials first, include irregular costs and leave room for ordinary surprises before deciding whether a quick loan instalment amount is realistic. The total repayment and due dates deserve the same attention as the money you receive. If you would like to discuss the terms or your budget questions, speak to a Loan4Debt consultant before making your decision.