
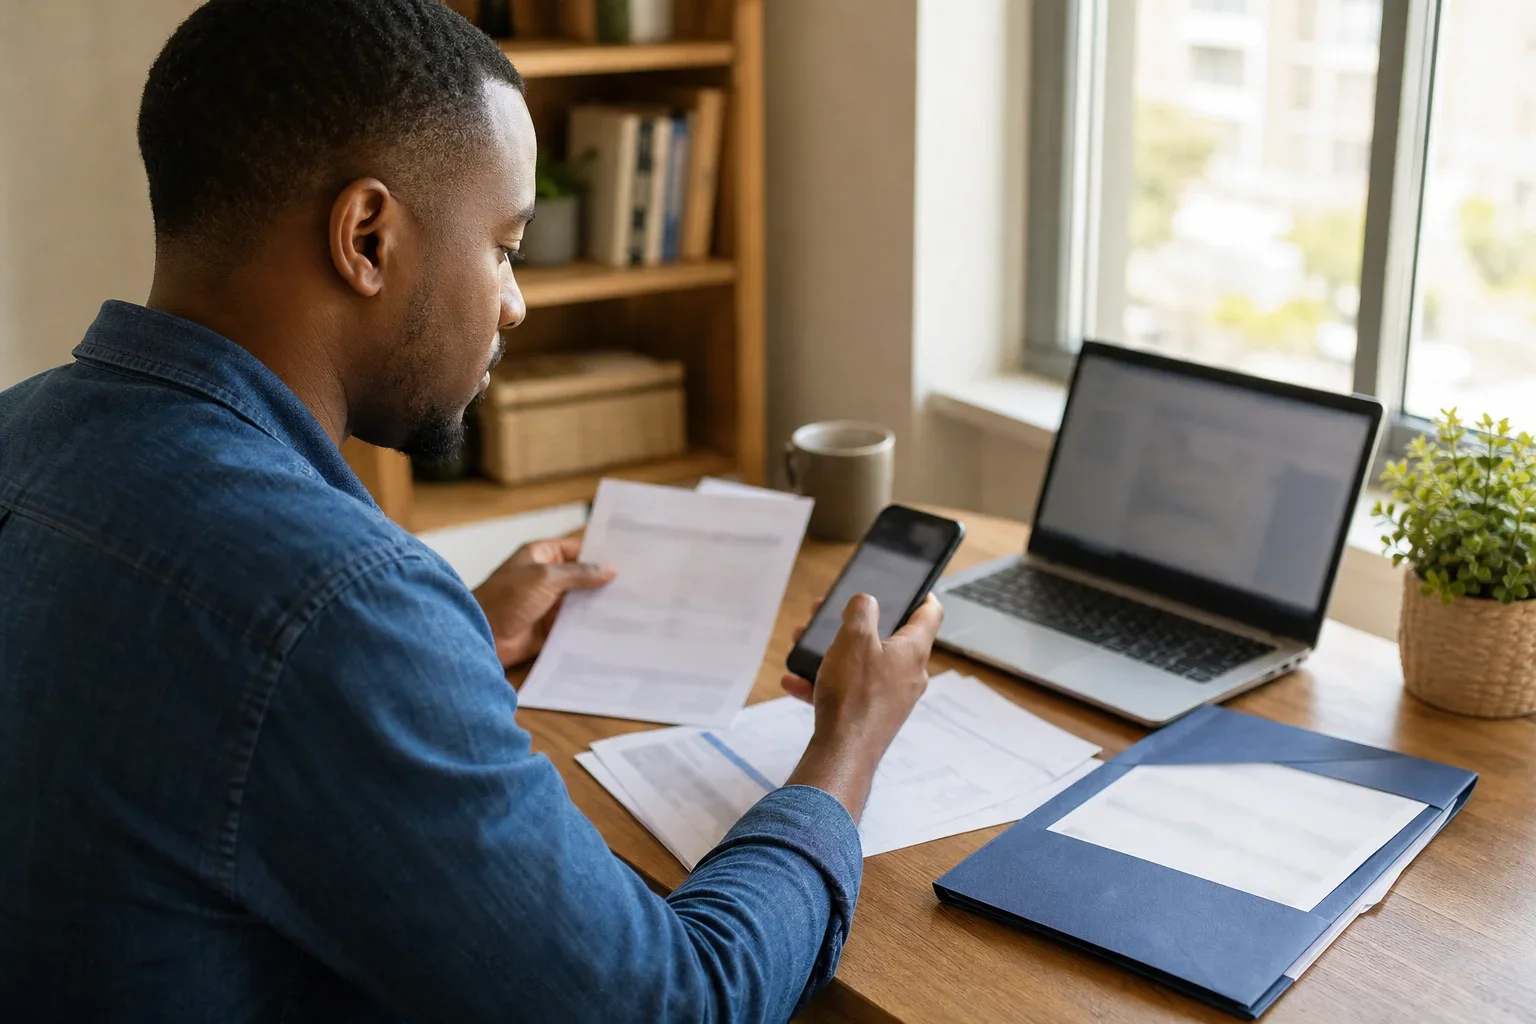
Documents needed for a quick loan can feel like a hurdle when you are already dealing with an unexpected bill or a tight month. In practice, preparing a few clear, current records before you start can make the application easier to complete and reduce unnecessary follow-up. Requirements differ between lenders and depend on your circumstances, but understanding the usual requests helps you answer questions accurately and protect your personal information along the way.
Documents needed for a quick loan usually include
The documents needed for a quick loan are generally used to confirm who you are, where you live, how money reaches your account and whether repayments are likely to fit your budget. A lender may ask for information online first, then request clear copies or digital statements where needed. Have the original documents nearby so that names, numbers and dates can be entered correctly.
Identity document
A valid South African identity document is commonly requested to confirm your identity. This may be a green barcoded ID book, a smart ID card or another accepted identification document, depending on the lender’s process. Check that the image is sharp, all four corners are visible and the details can be read without zooming in excessively.
Your name on the ID should match the name used on your bank account and application. If you have changed your surname or other personal details, do not guess which version to use. Explain the difference early and ask what supporting record may be required, rather than submitting mismatched information and hoping it will be accepted.
Proof of residential address
Some applications ask for proof of where you live. A recent utility bill, municipal account, lease document or bank statement showing your address may be accepted, but the acceptable document and how recent it must be can vary. Read the request carefully, because a document that shows an address but is outside the required date range may not meet the requirement.
If the household account is in somebody else’s name, do not alter it or submit it without context. Let the consultant know your living arrangement and ask which alternative record is suitable. The official South African Government portal is also a sensible starting point when you need to find public services connected with identity documents or address-related records.
Bank account details and statements
Lenders may need to verify the bank account into which approved funds would be paid and from which repayments may be arranged. This can involve account details and recent bank statements. A statement helps show regular income, normal account activity and existing commitments, giving the lender information to assess affordability rather than relying on a single figure entered in a form.
Download statements directly from your banking app or online banking profile where possible. Screenshots can cut off important details, hide the statement date or be difficult to verify. If you bank with Standard Bank, use its official website or banking channels rather than following a link from an unexpected message.
Proof of income
Proof of income shows how you receive money and how regularly it is paid. For someone employed on a salary, recent payslips may be relevant. Depending on the application, a bank statement showing the income deposits may also be requested so that the information can be considered alongside regular expenses and other repayments.
If you earn income through self-employment, contract work, commissions or another non-standard arrangement, gather the records that best show the pattern of income. These could include bank statements, invoices, payment confirmations or business records, subject to what the lender asks for. Be straightforward about changes in your income, because an accurate picture is more useful than trying to make a temporary high month look permanent.
The documents needed for a quick loan are not a promise of approval. They are part of an application that can be assessed for eligibility and affordability. Having them ready simply means you can provide clear information and better understand any question that comes back to you.
Preparing documents needed for a quick loan safely
Preparing documents needed for a quick loan safely means checking both the document itself and the way you send it. Financial and identity records contain private information, so convenience should not mean sending them through an unfamiliar channel. Use the application route or secure method confirmed by the lender, and pause if a request looks unusual.
Check every document before uploading
Open each file before you send it. Confirm that the full page is included, text is legible and the document date is visible. A photo taken in poor light, a cropped page or a file with glare may lead to a further request even when the underlying document is valid.
It also helps to check that your basic details are consistent across the application, ID, payslip and bank statement. Look at spelling, initials, account numbers and addresses. Small differences are not always a problem, but they are easier to explain before submission than after an assessor has asked for clarification.
Use a secure, verified route
Type the lender’s website address into your browser or use a saved, trusted link rather than responding to a random message. Check that you are communicating with the lender you intended to contact, especially before sharing an ID number, bank statement or account information. Be cautious of requests that create pressure or ask you to move the conversation to an unfamiliar platform.
Never send your banking password, PIN, card CVV or one-time password as part of a document request. These are security credentials, not supporting documents. If somebody asks for them, stop and verify the request independently through known contact details.
Keep useful copies, not unnecessary records
Save the documents you submitted in a secure folder so you can refer to them if a consultant asks about a date or figure. Keep track of when you sent them and through which channel. At the same time, avoid leaving copies of your ID and statements on a shared device or in an unsecured public email account.
Documents needed for a quick loan should be current, complete and relevant, not a large collection of unrelated personal records. Share only what is requested through the confirmed process. If you are unsure why a document is needed, ask for a plain-language explanation before providing it.
When documents needed for a quick loan are incomplete or outdated
An out-of-date record does not automatically mean you should abandon the application. First, identify why it may not meet the request: the issue could be an old statement date, an expired ID, a missing page or an address that no longer reflects where you live. Once you know the gap, you can ask what current alternative would be accepted.
Replace older statements and records
For a bank statement or payslip, the most practical answer is often to download the newest available version. Do not edit dates, cover information or combine pages in a way that makes the record unclear. If your latest income has changed, provide the current information and be ready to explain it honestly.
Explain a genuine difference in your details
Moved recently, changed jobs or updated your surname? These are normal life changes, but they can create a difference between documents. Tell the consultant which detail has changed and ask whether an additional supporting document is needed.
This approach is better than repeatedly uploading the same document after it has been queried. It gives the lender a clearer picture and helps you understand the next step. For people comparing options, the process information on quick loans can help explain how an online application is approached.
Review the commitment as well as the paperwork
Before you submit anything, take a moment to consider the reason for borrowing and what repayments could mean for your monthly budget. Documents support an affordability assessment, but you should also read the terms, repayment amount, fees and dates carefully if an offer is made. Ask questions about anything you do not understand before agreeing to a loan.
If an urgent expense is putting pressure on your budget, information about Urgent cash loans may help you understand a relevant option. An urgent need does not remove the importance of reviewing the repayment commitment. Clear documents and clear questions both support a more informed decision.
Frequently asked questions
1. Which identity documents may a lender ask for?
A lender may ask for a valid South African ID document to confirm your identity. The acceptable format can differ, so use the application instructions instead of assuming every document is treated the same way. Send a clear, complete image and make sure the personal details match the information in your application.
2. Why are recent bank statements often requested?
Recent statements can help show income deposits, normal spending patterns and existing financial commitments. That information can be relevant to an affordability assessment and to checking account details. The documents needed for a quick loan may therefore include statements for a stated recent period, rather than a single older record.
3. What can count as proof of income?
Recent payslips may be appropriate if you receive a regular salary. People with variable or self-employed income may be asked for statements, invoices or other records that show how income is received. The best document depends on your circumstances and the lender’s stated requirements.
4. How should I share documents safely online?
Use the lender’s confirmed website or approved secure channel. Do not share passwords, PINs, CVVs or one-time passwords, as these are not normal supporting documents. Review the recipient and web address before uploading, particularly if the request arrived unexpectedly.
5. What should I do if a document is out of date?
Download or request the newest version where possible, such as a current bank statement or payslip. If the issue is an expired ID or changed address, ask what alternative or updated record is required. Documents needed for a quick loan should reflect your current situation as accurately as possible, so it is better to clarify the issue than submit an unsuitable document.
Prepare your application records with confidence
Keep these practical points in mind before sharing personal and financial information.
◆ Use current, readable files
Check dates, full pages and legibility before uploading an ID, statement or income record.
◆ Keep details consistent
Review names, addresses and account information across your application and supporting records.
◆ Share through verified channels
Use a confirmed website or secure route, and never provide passwords, PINs, CVVs or one-time passwords.
◆ Ask before guessing
If a document is outdated or your circumstances have changed, ask what alternative record is appropriate.
Prepare clearly, then ask questions
Getting the documents needed for a quick loan in order can make the application process clearer and reduce avoidable delays. Use current, readable records, protect your sensitive information and be open about any differences in your details. Before accepting any offer, make sure you understand the terms and can realistically manage the repayments. If you are unsure which records apply to your situation, speak to a Loan4Debt consultant before submitting your application. For documents needed for a quick loan, careful preparation helps keep the next practical step clear.